 Joseph Louis Tan
About Joseph
An investor since 2019. A parent making these decisions too.
I'm Joseph Louis Tan, a father of two boys, a Singapore property agent with JNA Real Estate at PropNex, and before any of that, someone who spent twenty years in design and education sitting with people at the biggest decision of their working life.
Where my own money has been
Year by year.
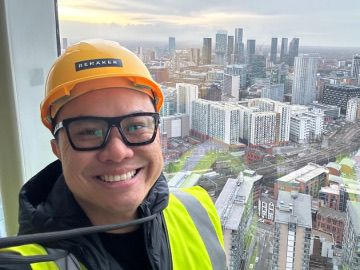
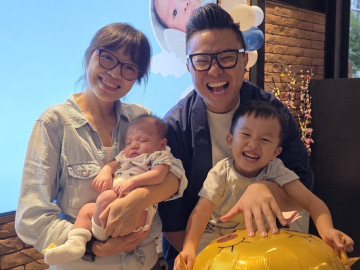
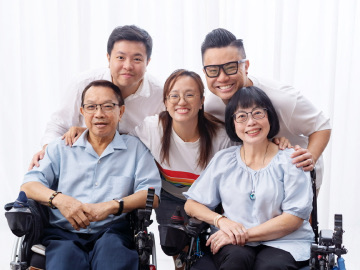
Personal investment experience as at September 2026, through individual, joint and shared holdings. These are not client transactions, and they are not a promise that anyone else will get the same outcome.
What it taught me
Four lessons, all of them expensive.
The number almost
nobody has run
Most people stop working around 65. Very few have worked out what that costs.
If you are 35, that is 30 years away, which is easy to file under someone else’s problem. The trouble is that the number is much larger than it looks, and the only cheap thing you have right now is time.
The sum, with round numbers so you can see the shape
- A family of four, and $10,000 a month covers the life you have today.
- In 30 years, at 3% inflation, that same life costs about $24,000 a month. Inflation roughly doubles it every 25 years or so.
- That is around $290,000 a year you need to produce without working.
- To draw that down safely, the pot behind it has to be in the region of $7M.
- CPF and savings, at the rate most families save, land somewhere between $1.5M and $2M. CPF pays out for life and it is counted in that figure. For most families it covers a part of what they actually spend, not the whole of it.
- The difference is the gap, and it is the number almost nobody has looked at.
Illustrative, with round numbers. Yours will be different, and working out which parts are different is most of the first hour.
Saving harder does not close a gap that size. What changes the arithmetic is leverage. Property is the one asset here that a bank will lend most of the purchase price against, which means inflation works on the whole value rather than only on the part you paid for. Used carelessly that cuts the other way, which is why holding power gets tested before anything is shortlisted.
So property belongs in the conversation. That is not the same as saying property will get you there, and I am not going to tell you it will. Whether it helps your family depends on your numbers, your timeline, and what you could carry through a bad year. That is what we work out, and sometimes the answer is that the move you were considering makes the gap worse.
Why this is the thing I care about
I watched the generation before us end up in exactly that position. They did everything right. Worked hard, paid off the flat, raised their children in it. On paper they are wealthy. In practice the money is locked inside the walls and inside CPF, and you cannot pay for groceries with a valuation.
There is no blame in that. Nobody taught them another way, and they sacrificed so that we could learn one. I learned it at home, watching my parents work their whole lives to give us more than they started with. That picture is what I am planning against for my own family, and it is where the word safely comes from.
My goal is to help 1,000 Singaporean families retire safely through property. Safely is the word that matters. It means your family is never one bad year from a forced sale.
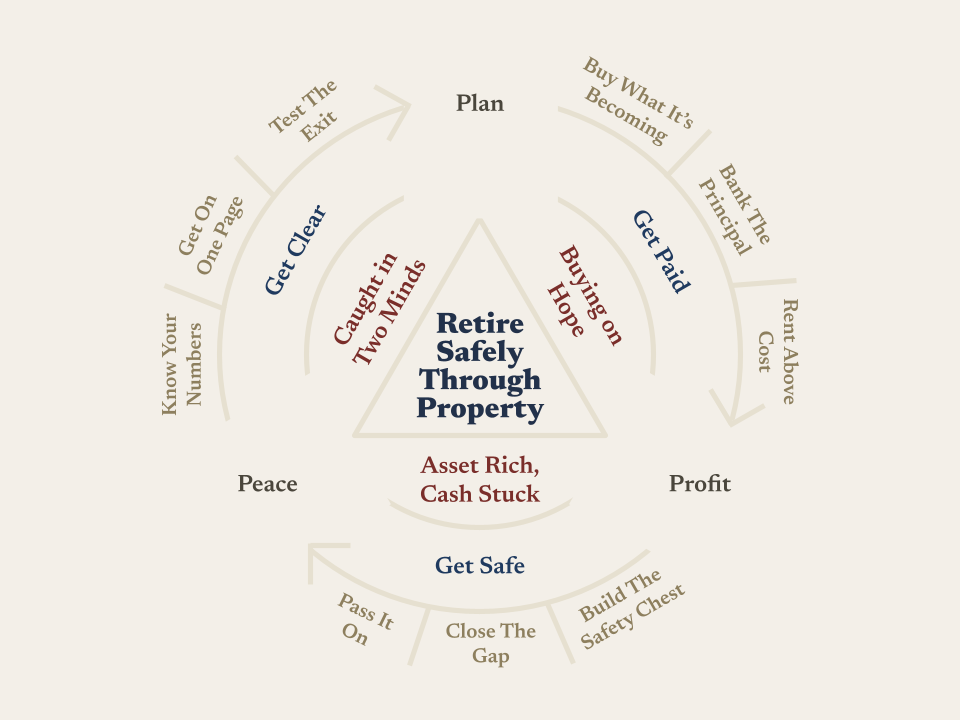
The Family Property Plan
The map my own family uses.
This is the map my own family uses to get there. Three milestones, nine missions. I walk through every part of it in the video, so you can score your own situation as you watch.
If the score raised a question, that is the reason to talk.
Bring your rough numbers, and come together if you are deciding as a couple. We will look at where you actually stand, and what is worth checking next.
Book a free consultation →The team behind the method
My experience is mine. The method is the team's.
I work inside JNA Real Estate, the six-time champion team in PropNex, led by PropNex's overall champion producer. The structured process I use to understand your needs, check the numbers and compare directions is the team's, and it sits behind more than 3,500 homes the team has transacted. Where a case would benefit from a second pair of eyes, I can bring in a senior colleague. That is arranged case by case. I remain your point of contact and I explain the reasoning behind every recommendation myself.