 Joseph Louis Tan
Right at the gate
Baci Baci Ristorante Italiano · Chu And · Little Bear's House · BASE Training · LOUE Bicycles Fit Lab
Sold · One bedroom · October 2026
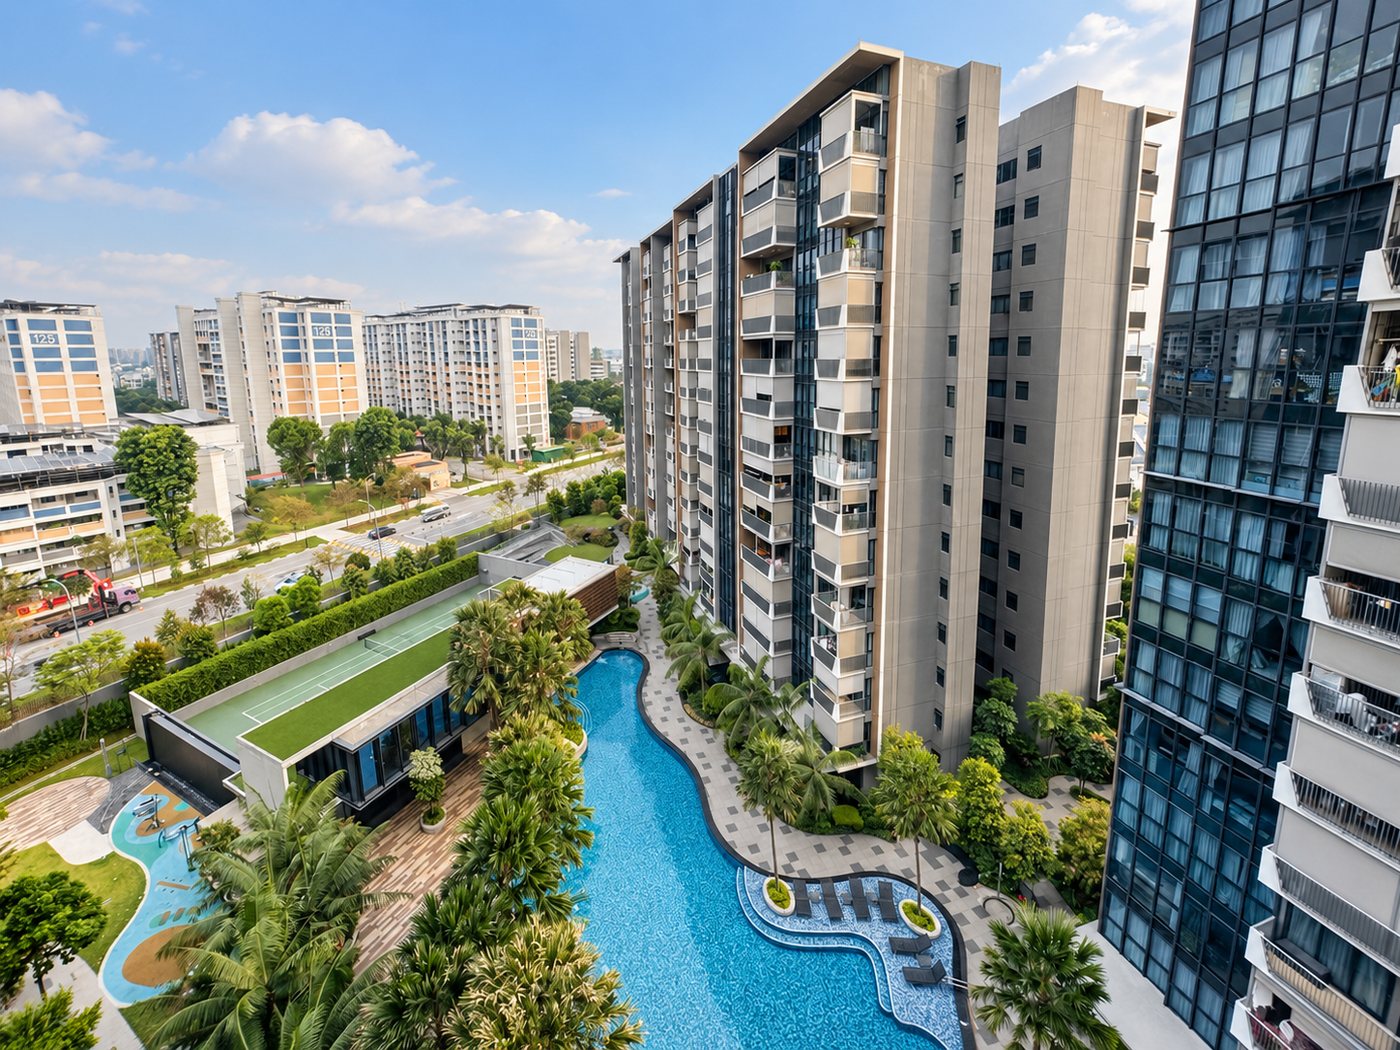
452 sq ft, one bedroom, high floor, facing the pool. Sold at the first viewing, October 2026, with no electricity or water connected in the unit and 17 other one-bedroom listings in the project at the time. 1 Serangoon North View, District 19. The report stays up for anyone weighing the development. Below: the unit, the numbers, what it returns on each way of financing it, and what 119 residents actually say about living here.
01 · What residents actually say
I read all 119 Google reviews for this project, not the 21 on the portal. The score is 4.5 out of 5, and the theme that repeats, across both platforms, unprompted, is quiet. On PropertyGuru, "Peace & Quiet" is tagged in 14 of 21 reviews, the top tag by a distance.
"Peaceful surroundings and easy access to nearby town centre. An oasis in a neighbourhood."
"The serenity is not anywhere you can find. And it smacks right in the middle between Serangoon North and Chomp Chomp area, which enjoy the benefits of both."
"Quiet, not facing any expressway."
The second most repeated observation is wind, a north-south orientation with low-rise landed housing all around. Residents mention it without being asked. Pet-friendly comes up twice, a full-sized tennis court twice, and the rooftop at National Day more than once.
02 · The back gate
Step out of the Lichfield Road back gate and you are already somewhere. I walked it.
Baci Baci Ristorante Italiano · Chu And · Little Bear's House · BASE Training · LOUE Bicycles Fit Lab
Chomp Chomp Centre · Serangoon Garden Market · Little Farms · oblong · The Aftertaste · Apollo Coffee Bar · myVillage
03 · The MRT question, answered honestly
Across both review platforms, the recurring criticism is distance to an MRT. It is a fair point today, and the Cross Island Line changes it.
Serangoon North (CR9)
About 600m · 8 minutes
2030
Most listings mention the Cross Island Line. Few mention the date. Whether 2030 works depends entirely on your timeline, and you should decide that before you view, not after. In the meantime: buses 73, 136, 315 and 317 from the stop on Lichfield to Serangoon MRT and NEX, plus a free shuttle.
04 · What it actually costs to hold
For a one-bedroom unit at $818,000, so you can see what you would actually clear each month rather than guess at it.
| Maintenance | $1,079.10 / quarterabout $360 a month including GST |
| Instalment at 1.75% fixed75% loan of $614,166 over 30 years | $2,194 / month |
| Same loan at 2.15% floating3-month SORA 1.135% plus a 1.0% spread | $2,316 / month |
| Property tax, non-owner-occupied | about $370 / month |
| Letting agent, half a month a year, spread | about $119 / month |
| One-bedders here let in 2026 at | $2,700 – $3,150 / month |
The arithmetic barely moves across the current asking range for this size. Thirty thousand dollars of price difference changes the gross yield by about a quarter of a percentage point. What actually moves your return is the rate you secure and how long you hold.
The portal shows a 2.6% yield for this project. That is the average across every unit size and the larger units drag it down, the one-bedders run about 4% gross. Gross yield is only half the picture, and the missing half is the bigger one. On a 75% loan the tenant repays $15,706 of your principal in the first year. Cash flow sat at roughly −$240 a month at the $2,800 the unit was fetching, so the unit still builds about $13,000 in year one, which is 6.4% on the cash you put in.
One hundred one-bedroom leases were signed here between February 2025 and August 2026, sixty-three of them in this size band. The 2026 median is $2,825 and the range is $2,700 to $3,150. Rents here have held steady for two years rather than climbed: the median in this size band was $2,800 in 2025 and $2,825 in 2026. What has changed is where the most recent leases are landing. In August 2026, the latest month on record, the top lease in this size band was $3,150, and both of the larger one-bedders let at $3,100. Here is the same cost stack across that range, on the 1.75% fixed rate.
| Monthly rent | Gross yield | Cash, monthly | Principal repaid, yr 1 | Built in yr 1 |
|---|---|---|---|---|
| $2,700 | 3.96% | −$343 | $15,706 | +$11,590 |
| $2,825 | 4.14% | −$218 | $15,706 | +$13,090 |
| $2,900 | 4.25% | −$143 | $15,706 | +$13,990 |
| $3,000 | 4.40% | −$43 | $15,706 | +$15,190 |
| $3,150 | 4.62% | +$107 | $15,706 | +$16,990 |
Costs held constant across every row: instalment $2,194, maintenance $360, property tax $370, letting agent spread at $119. Principal repaid is the first-year loan reduction on a $614,166 loan at 1.75% over 30 years. Rent figures are the observed range for 400–500 sqft in this development, not a forecast. This unit was fetching $2,800. Refreshed 27 Sep 2026; sold Oct 2026, figures updated 8 Oct 2026.
Read the last column, not the third. The unit builds money in year one at every rent in the observed range, because the tenant repays your loan whether or not there is cash left over each month. On $204,722 of cash in, $13,090 built is 6.4% on your money. Cash flow is close to neutral and turns positive at the top of the range. If you would rather have the cash each month instead, a 55% loan or an outright purchase gives you that.
Those 63 leases span every floor and every facing in the development. This one is high, with the pool in front of it. You are not letting an average unit here, and the range above is an average range.
You are not inheriting a tenancy set by somebody else in 2024. It completes empty, so you furnish it, photograph it and market it on your own terms into the next leasing cycle.
Rents here are flat. The median for this size moved from $2,800 to $2,825 across a year — under one per cent, over 63 leases. So if anyone tells you the plan is to re-let higher and let the rent growth carry the return, ask them for the number. The upper half of that range is available because of what this specific unit is, not because the market is moving. The return here is principal paid down and what the price does over your holding period, and both of those are in the next section.
05 · So is it actually a good investment?
Most conversations stop at the yield figure. Here is the whole thing, at the $818,000 it sold for, let at $2,800, inside the 2026 range for this size, on a 1.75% fixed rate, in the first year.
| What you top upRent, less instalment, maintenance, property tax and letting fee | −$2,916about $240 a month |
| What you quietly put away$1,307 a month of that instalment is principal, your money, not the bank's | +$15,689 |
| Net, before the price does anything at allOn the $226,440 of cash and CPF you put in | +$12,773 · 5.6% |
| If prices fall 2% | −$2,952 · −1.3% |
| If prices don't move at all | +$13,408 · 5.9% |
Two different measures of this project's price history exist and they do not agree. Per-square-foot across the project has moved about 2.0% a year over the last three years. Resale prices since owners collected keys have moved considerably less, closer to 1% a year. I have shown both rather than pick the flattering one. Plan on the lower.
Even if the price falls 2% in your first year, you are only down 1.3%, because the principal you repaid absorbs almost all of it. That cushion is invisible in a rental yield, and it is the single biggest reason a modest-yield property can still be a sound one.
People assume the price you pay to get in decides everything. On a 30-year hold it moves less than you would think.
| Price | Per sq ft | Gross yield | Cash in | Return if flat |
|---|---|---|---|---|
| $818,000 | $1,810 | 4.18% | $226,440 | 5.9% |
| $830,000 | $1,836 | 4.12% | $229,800 | 5.8% |
| $850,000 | $1,881 | 4.02% | $235,400 | 5.5% |
Paying $32,000 more moves your first-year return by four tenths of a percentage point. What actually moves it is the rate you secure and how long you hold. That is worth knowing before you spend three weeks negotiating over a number that changes your outcome by less than a rate move would.
Whether any of this is a good trade depends on what else that $226,440 would be doing, and on whether you are comfortable with a payment that rises if rates do. That is the conversation worth having, and a yield percentage cannot hold it on its own.
06 · How this project got here
Keppel Land and Wing Tai paid the highest price for an outside-central-region site in that cycle, then launched in 2018 at roughly $1,635 per square foot when comparable projects nearby were at $1,300 to $1,400. The market said no. Only about 10% of the units sold in the first year, around 60 of 613.
Units only started moving in 2020 and 2021, once prices across the region had risen enough that Garden Residences no longer looked expensive.
The people who did well here were not the first movers. They were the ones who bought later, at lower prices, and held for a shorter time. Buying an existing unit today is that position, not the 2018 one. Anyone quoting this project's launch-buyer returns at you is describing a different purchase from the one you would be making.
In January 2026 a consortium of CapitaLand Integrated Commercial Trust, CapitaLand Development and UOL was awarded the Hougang Central mixed-use GLS site for about $1.5 billion, a land rate of $1,179 per square foot per plot ratio. It is the first government land sale parcel in Hougang since 2019. The plan is roughly 830 homes, plus about 300,000 square feet of retail, the largest mall in Hougang, a new bus interchange and a town plaza, all connected directly to Hougang MRT, with a Cross Island Line link planned for 2030. Completion is targeted for 2030 or 2031.
The land rate is the number worth holding on to, because you can work forwards from it. Add construction, financing and marketing, then the margin a developer needs to justify the risk, and a launch there would have to sell well above today's resale prices here. Today's OCR new-launch average is already about $2,260 per square foot. Set that against $1,812 here.
Two other things about that tender are worth more than the headline. The winning bid was one of three, and the two it beat came in at $1,155 and $1,100 per square foot per plot ratio. Three separate consortiums, bidding independently, priced this land within seven per cent of each other. That is not one developer being optimistic about Hougang. That is a consensus. And the buyers of it are CapitaLand and UOL, who are not in the business of speculative bets on estates they expect to stay flat.
Hougang Central is the next town centre over, not this doorstep. This unit's node is Serangoon and NEX, and that does not change in 2030. New supply priced higher does not lift existing prices on its own, resale still trades at a discount to new. What changes is the number that discount is measured from, and how a District 19 address reads to a buyer once the northeast has a mall of that size and a second rail line running through it. On a four to eight year hold, that is the part of this purchase I would actually underwrite. The rent is not going to do it.
It is also worth knowing plainly: the developer's break-even here was about $1,512 per square foot. Today's resale sits roughly twenty percent above what it cost to build. That is a reasonable place for a five-year-old building to be, and it is a long way from the froth you see in newer launches.
07 · What it takes to own it
Figures assume a Singapore Citizen buying a first residential property at $818,000. Your own position will differ, and that is the conversation worth having early rather than late.
| Minimum cash, 5% | $40,944 |
| Balance downpayment, 20%, cash or CPF | $163,778 |
| Buyer's Stamp Duty | $19,167 |
| Legal fees, typical | $2,800 |
| Total upfront | $226,689 |
If this is a second property, ABSD adds $163,778 on top.
| Maximum loan, 75% LTV | $614,166 |
| Assessed at the 4% MAS floor | $2,932 / mo |
| Gross income needed | $5,331 / mo |
| With a $500/mo car loan | $6,240 / mo |
TDSR caps total debt servicing at 55% of gross income.
Banks do not assess you at 1.75%. They stress-test at a 4% floor set by MAS, which is why the income figure looks high next to what you would actually pay. Get an In-Principle Approval before you view seriously. It tells you the real loan you can draw, and it is what lets you move on an Option to Purchase in days rather than guess and lose the unit.
08 · Inside a one-bedder
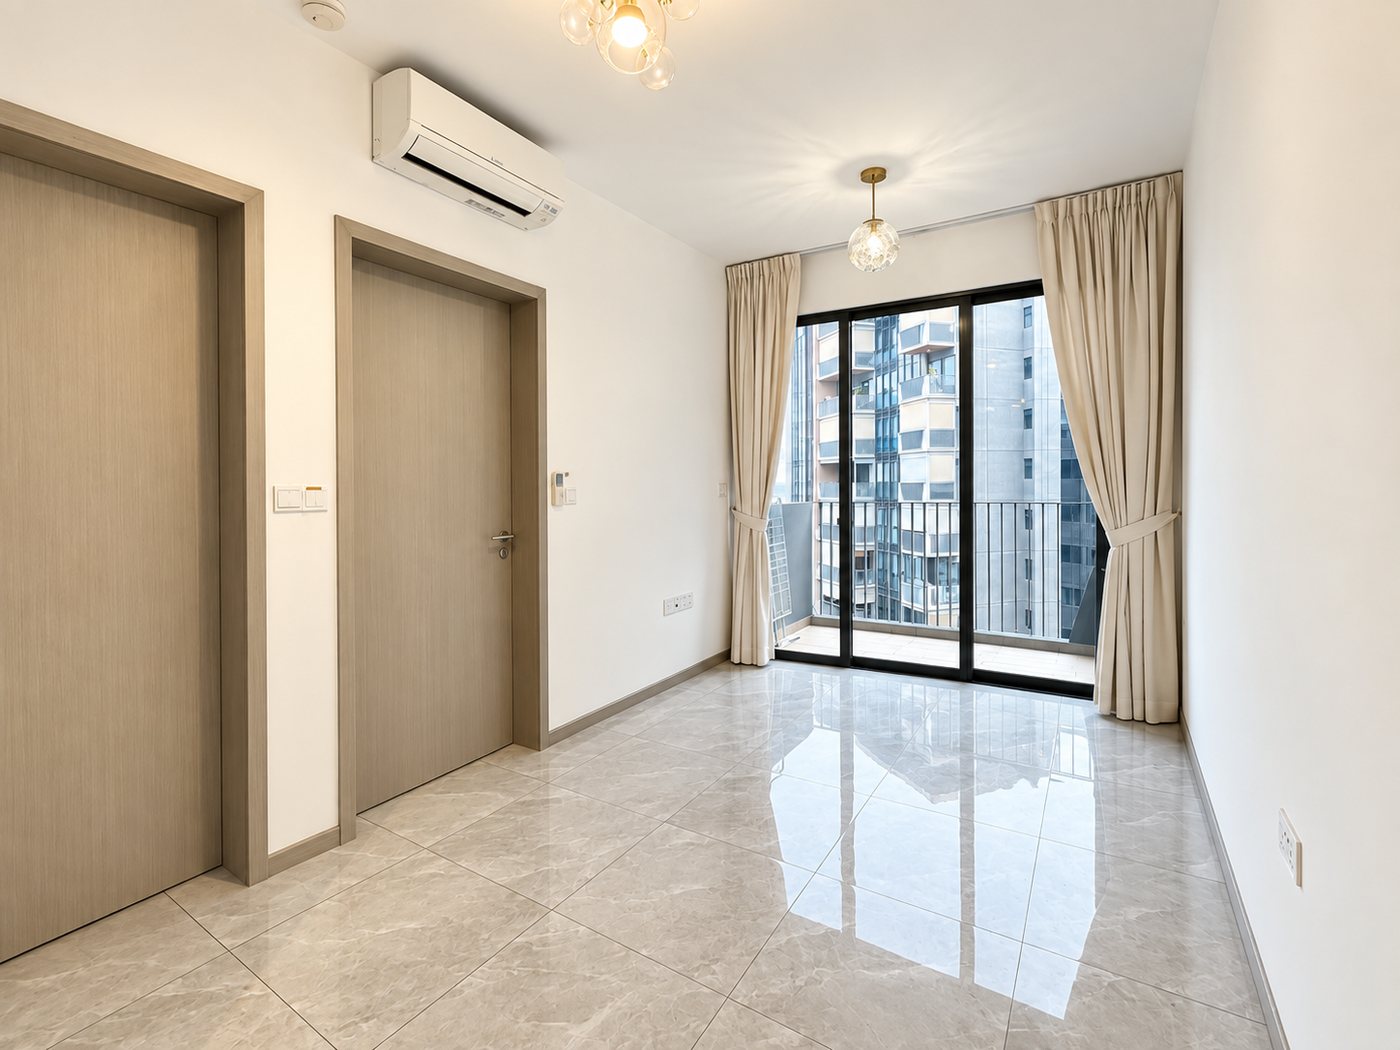
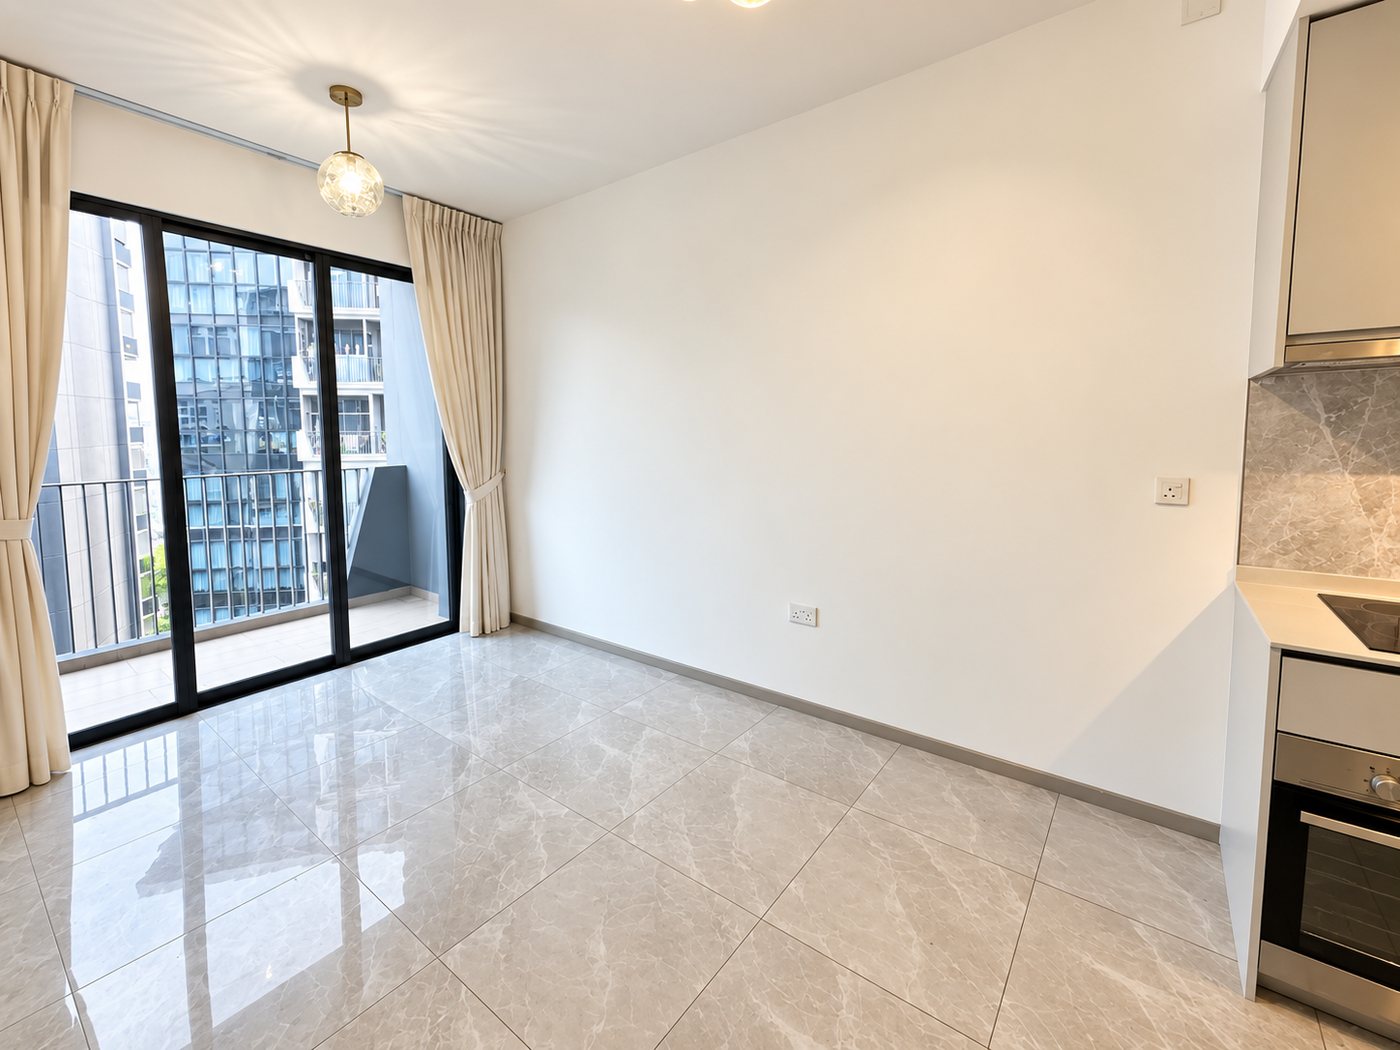
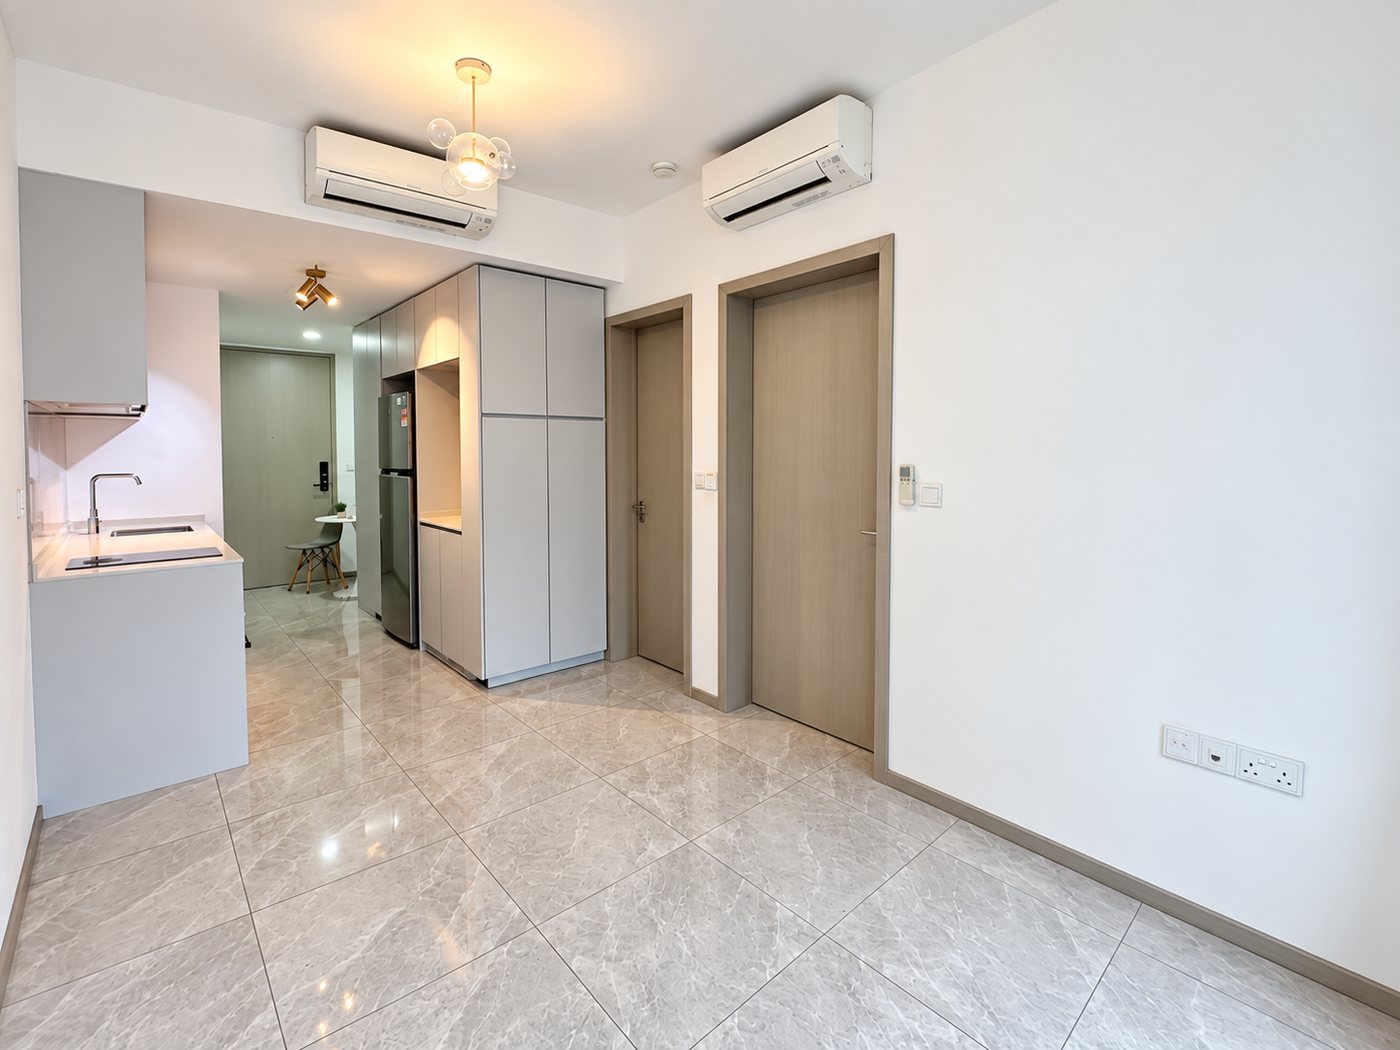
A one-bedroom on a high floor, facing the pool. It is vacant now, so there is no tenancy to inherit and no rent set by somebody else in 2024. Move in on completion, or furnish it and let it at today’s market. Photographed on site, 24 September 2026.
The whole unit, end to end. Entry, kitchen, living, the window, the bedroom, the bathroom, and the view.
It is empty in the video because it is empty now. No tenant, no furniture to work around, nothing to wait for. What you see is what you would collect the keys to.
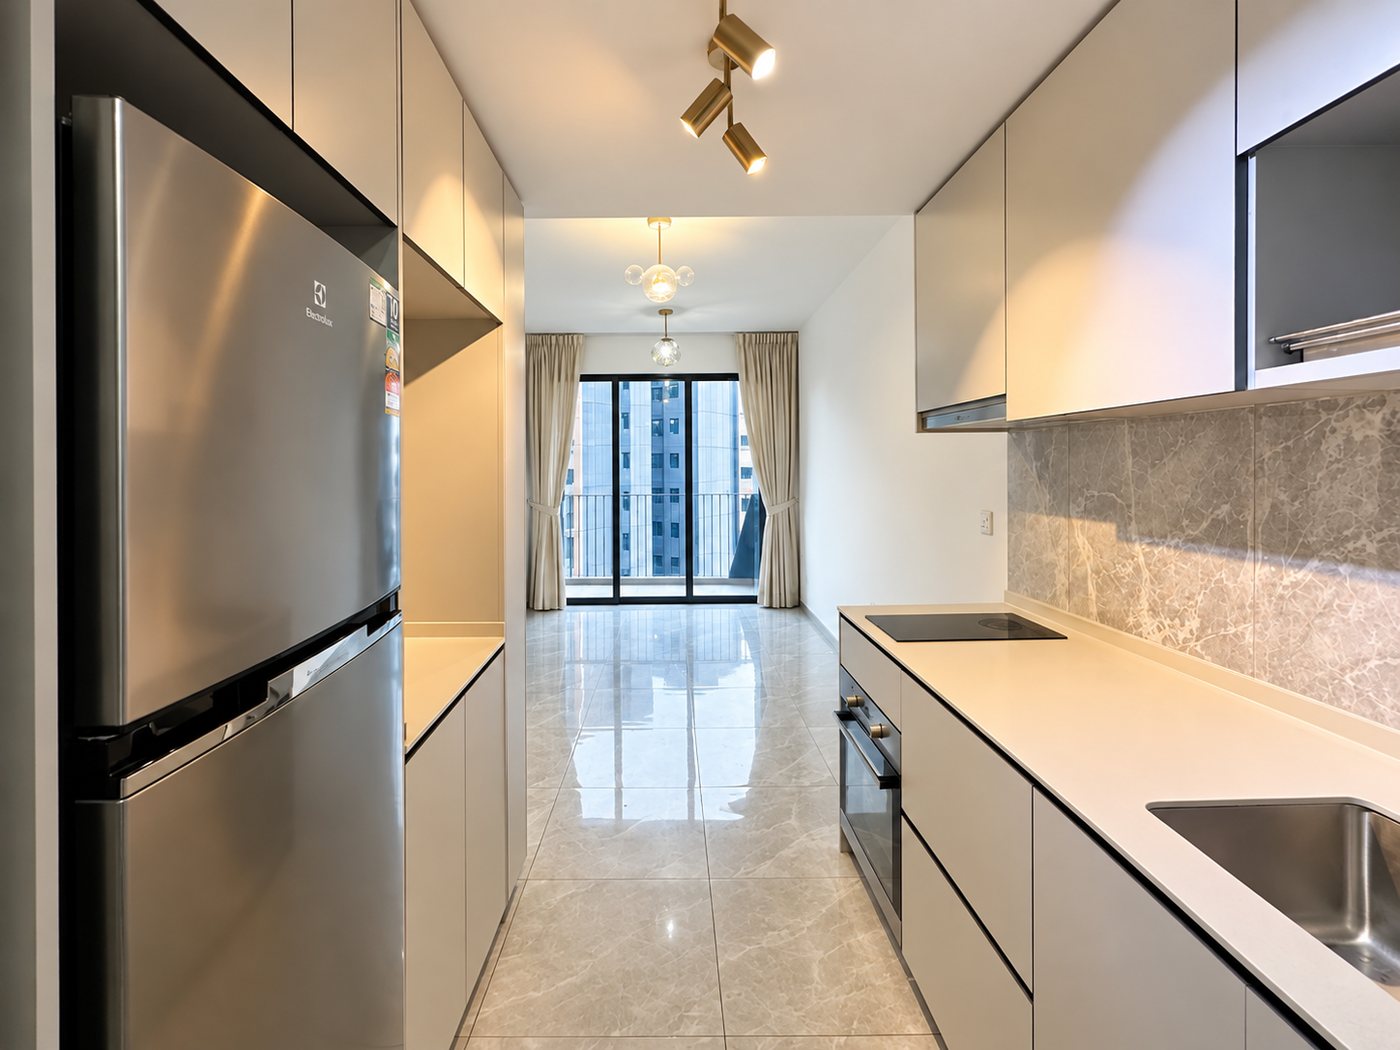
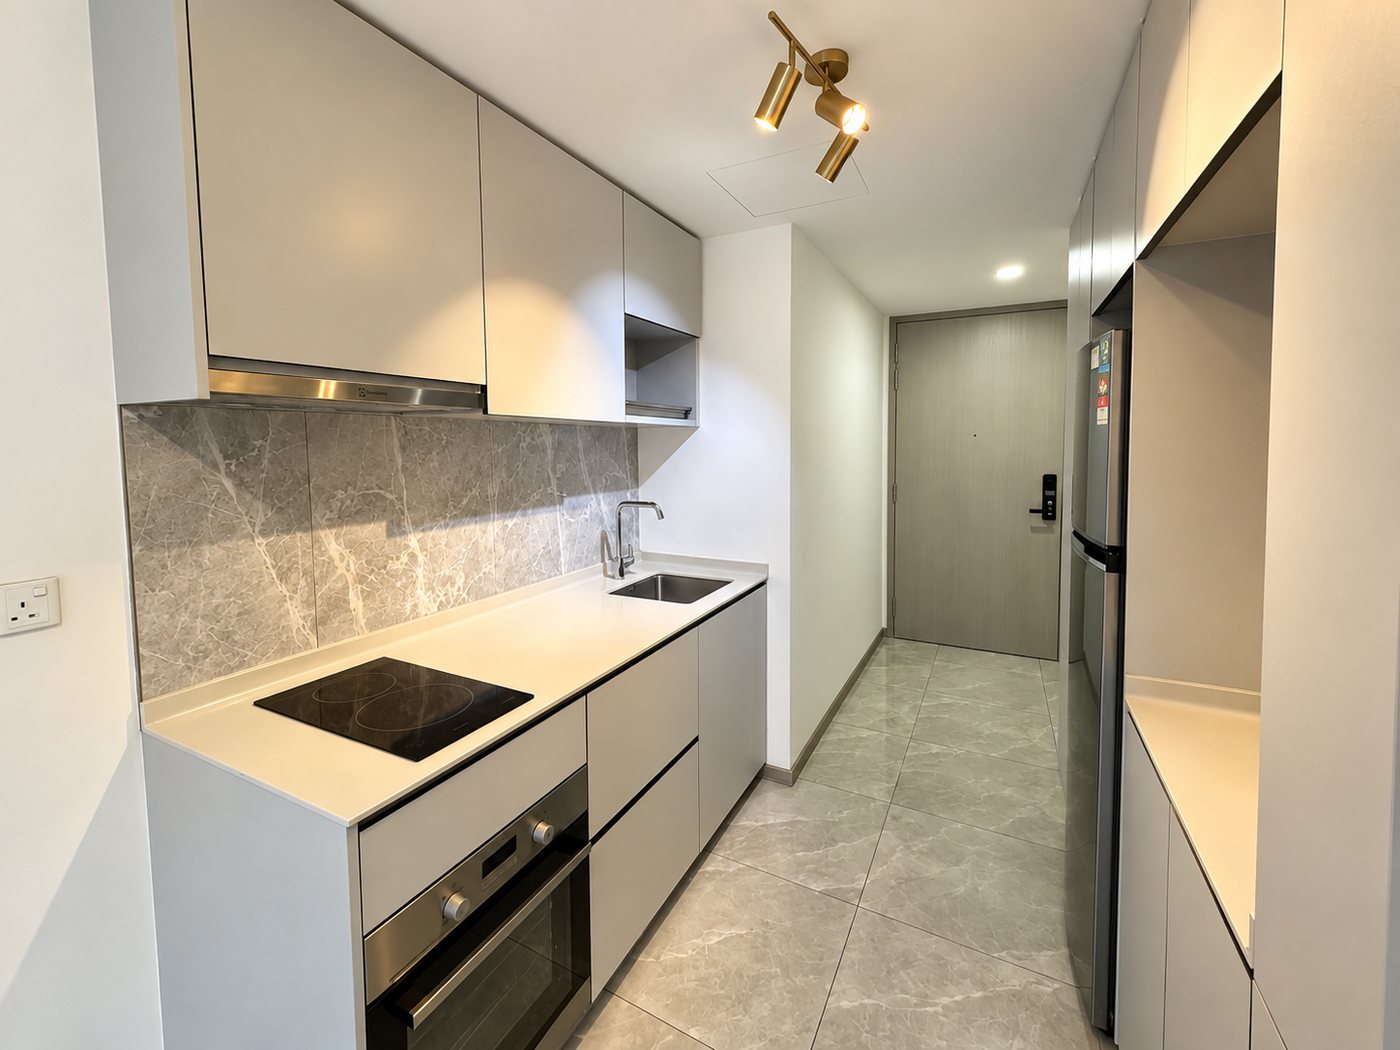
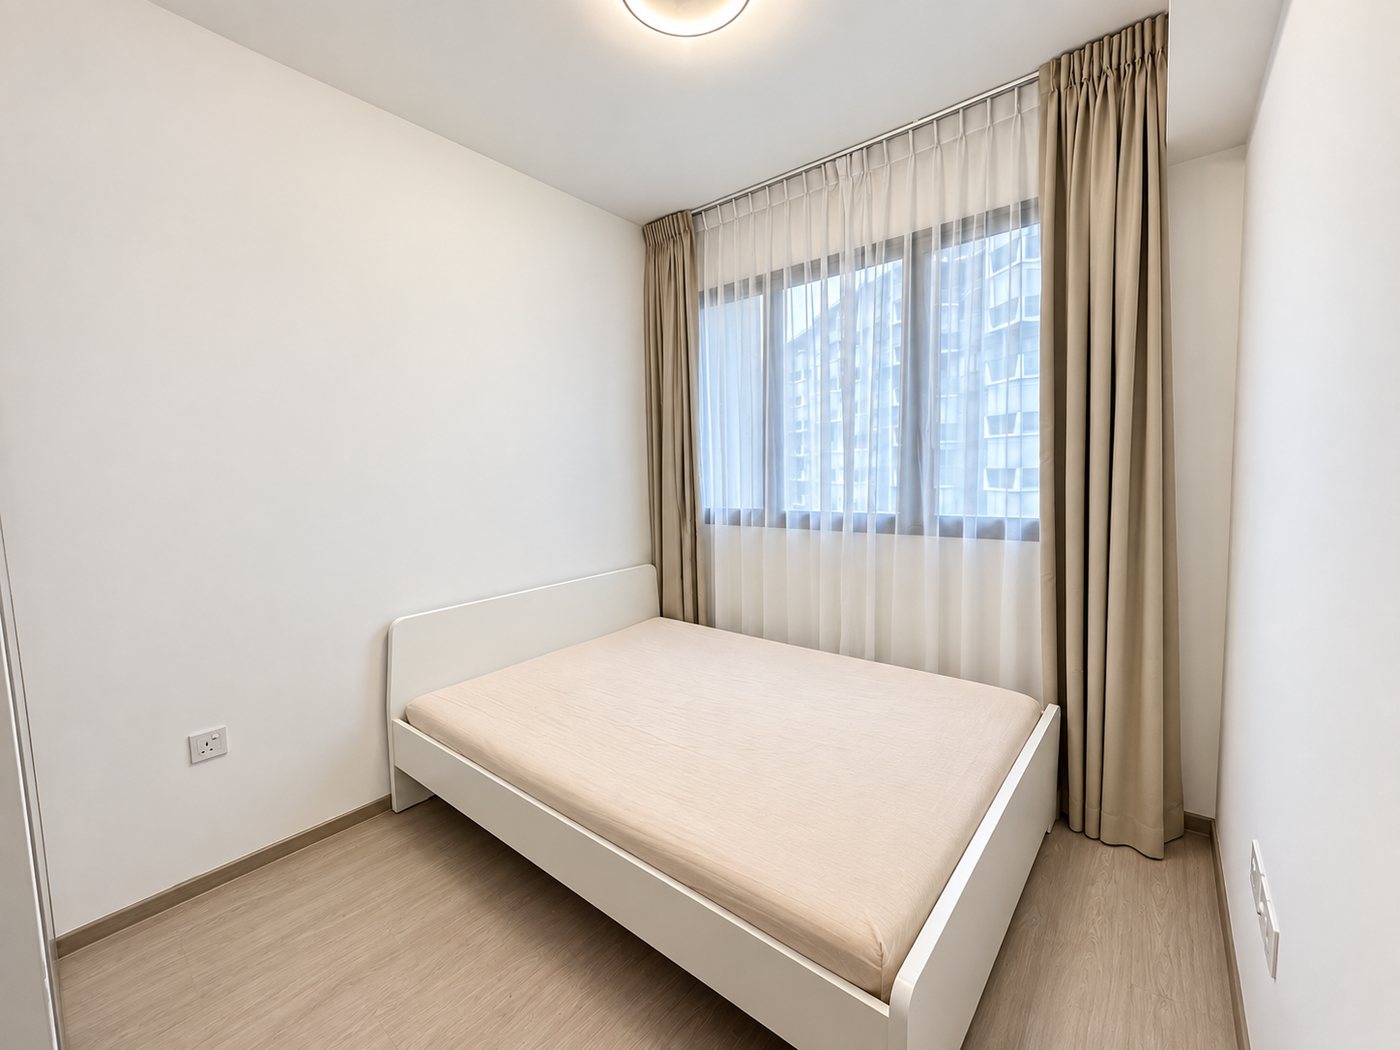
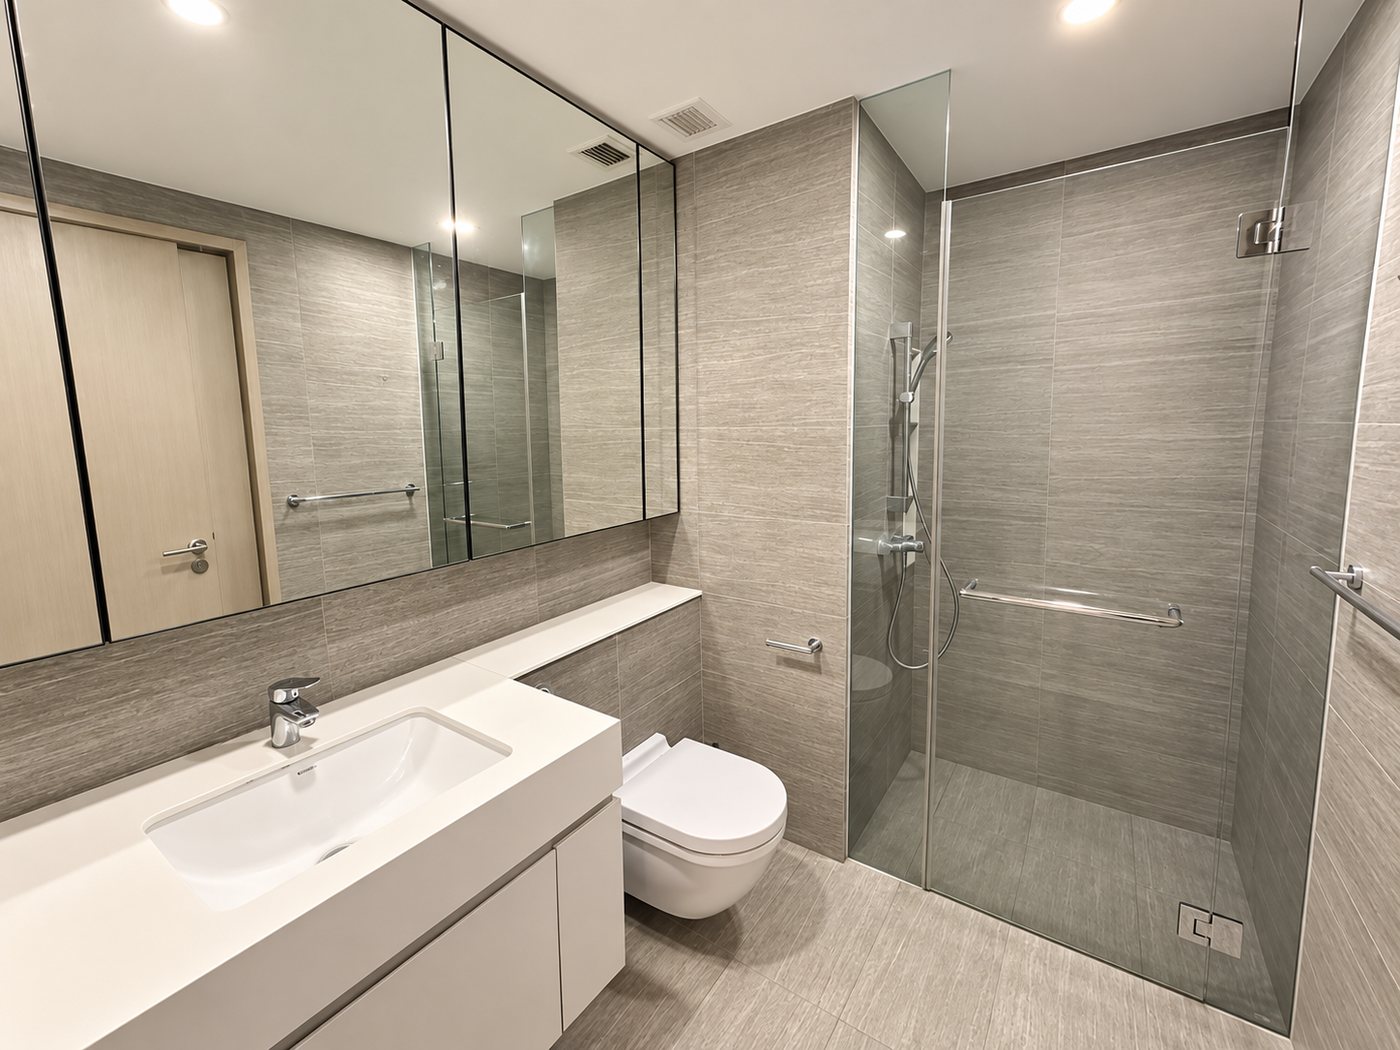
And the facilities, photographed the same morning.
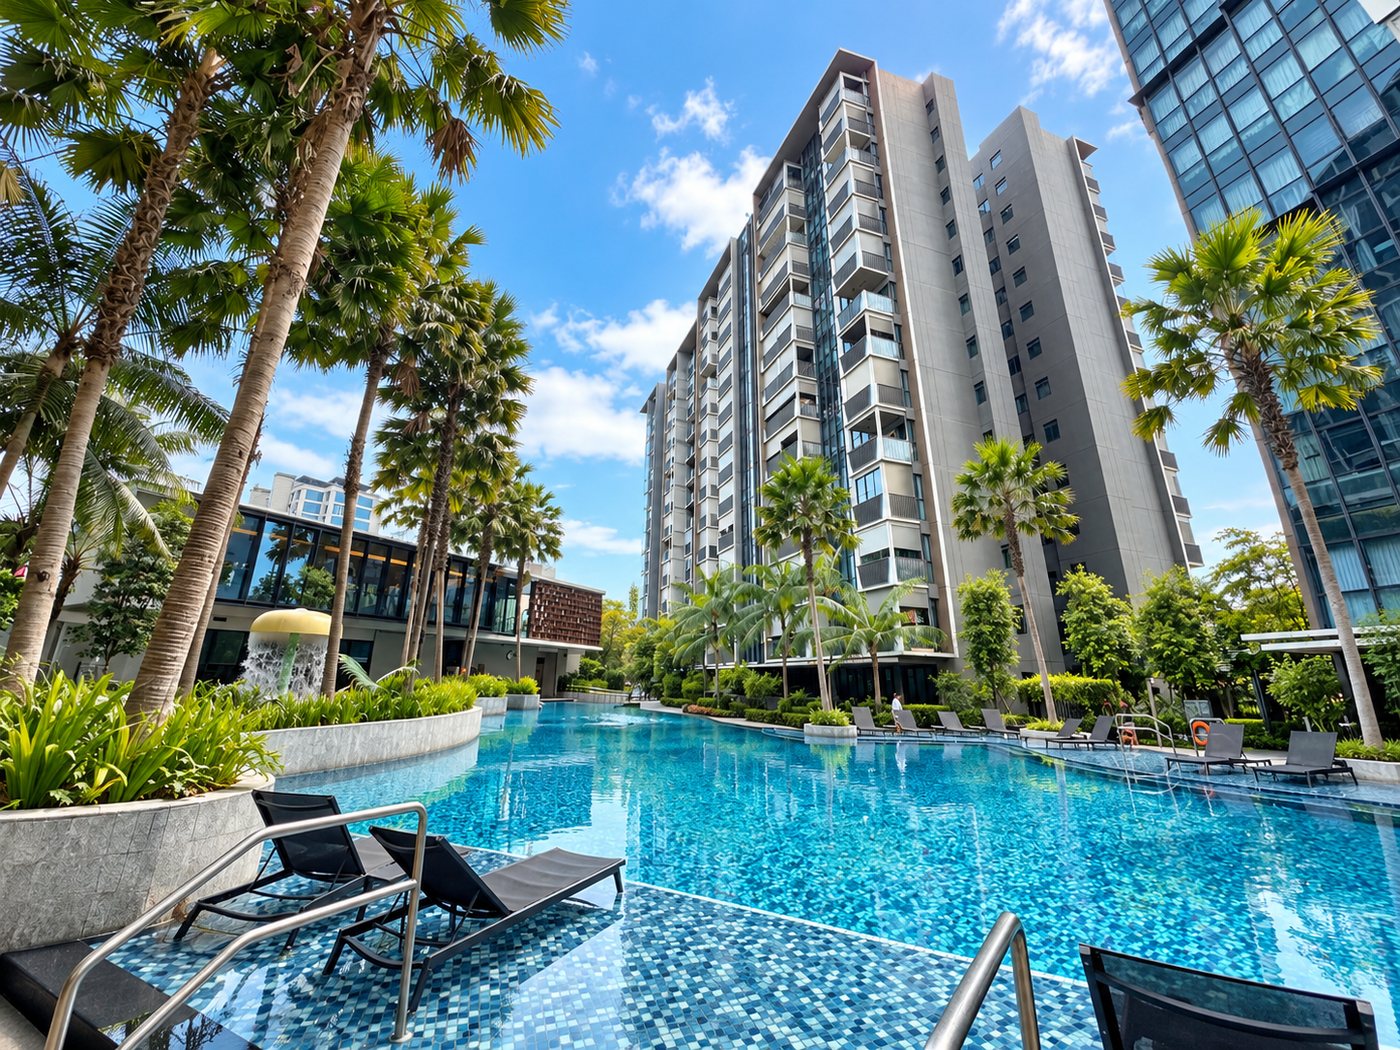
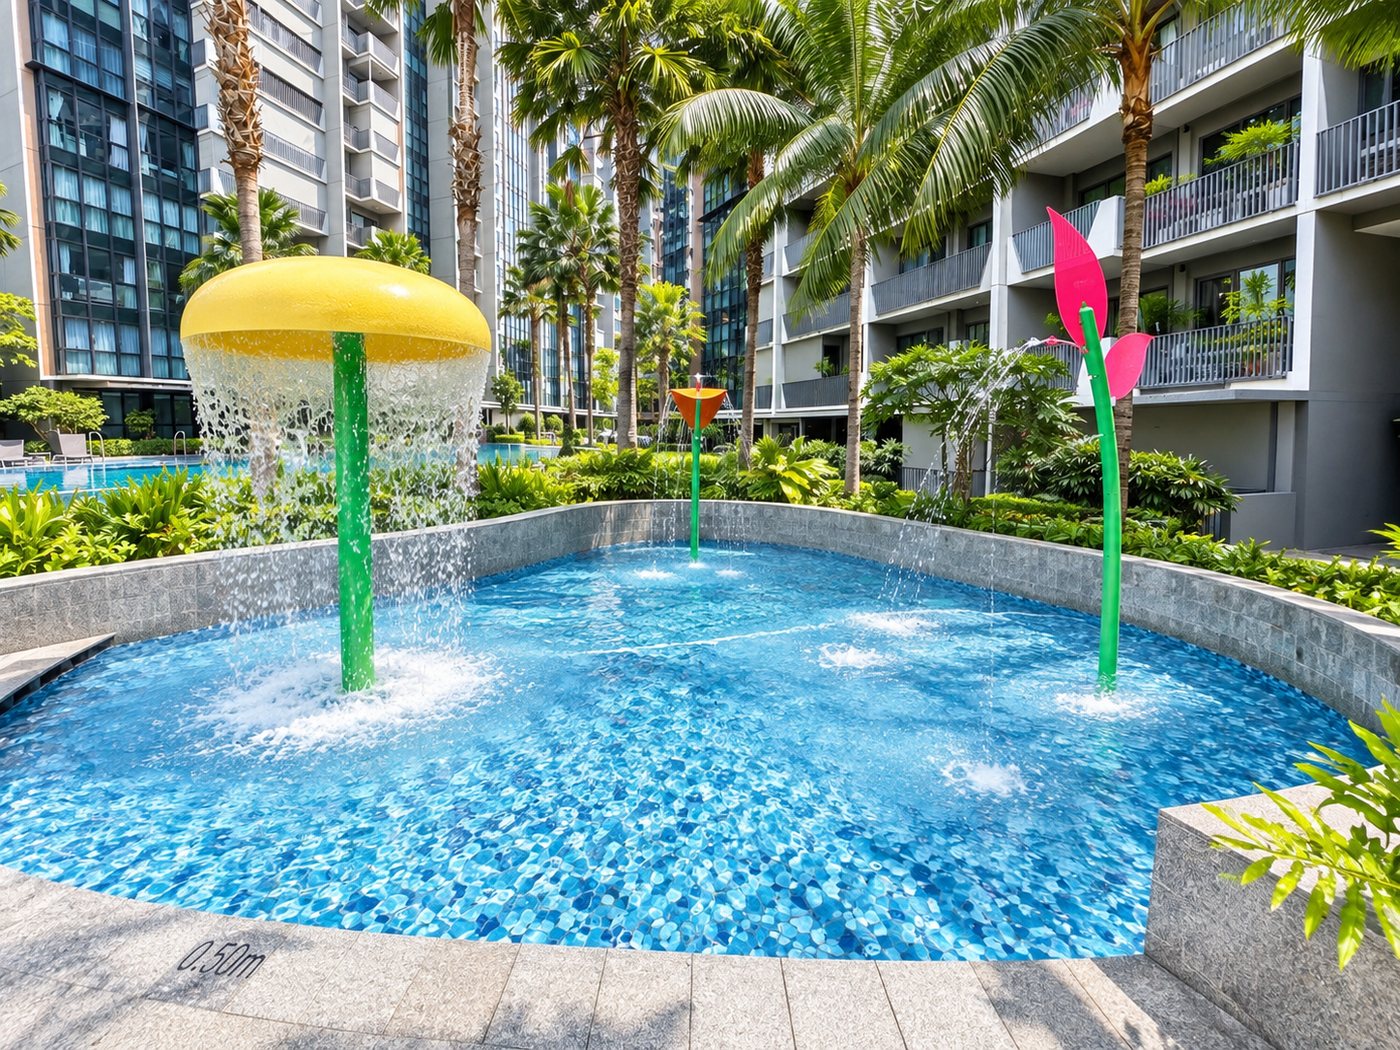
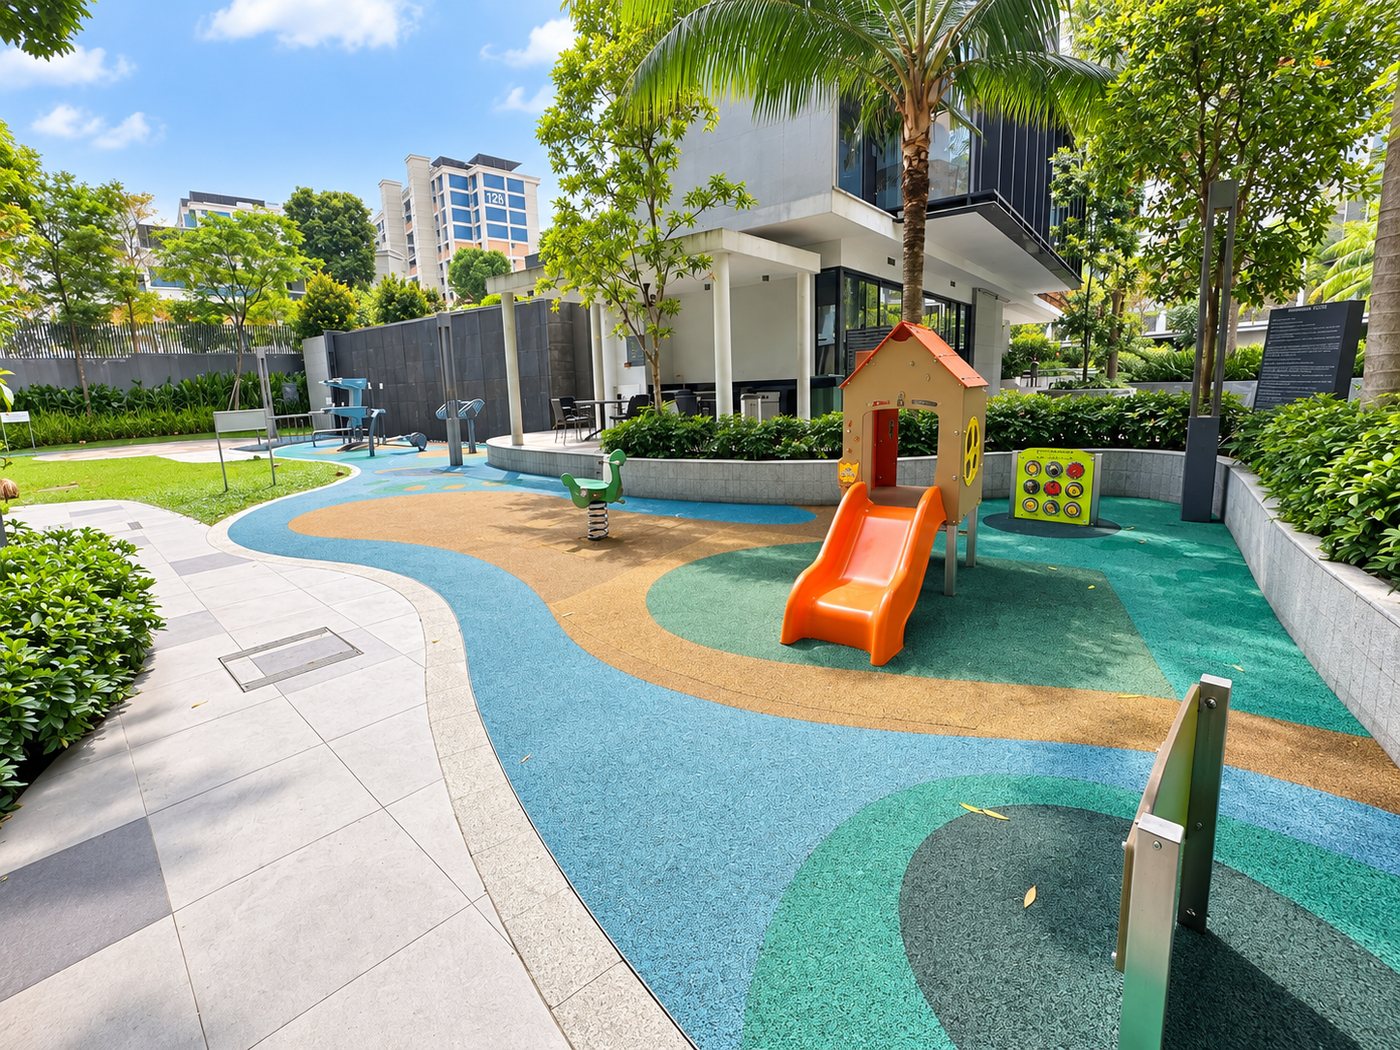
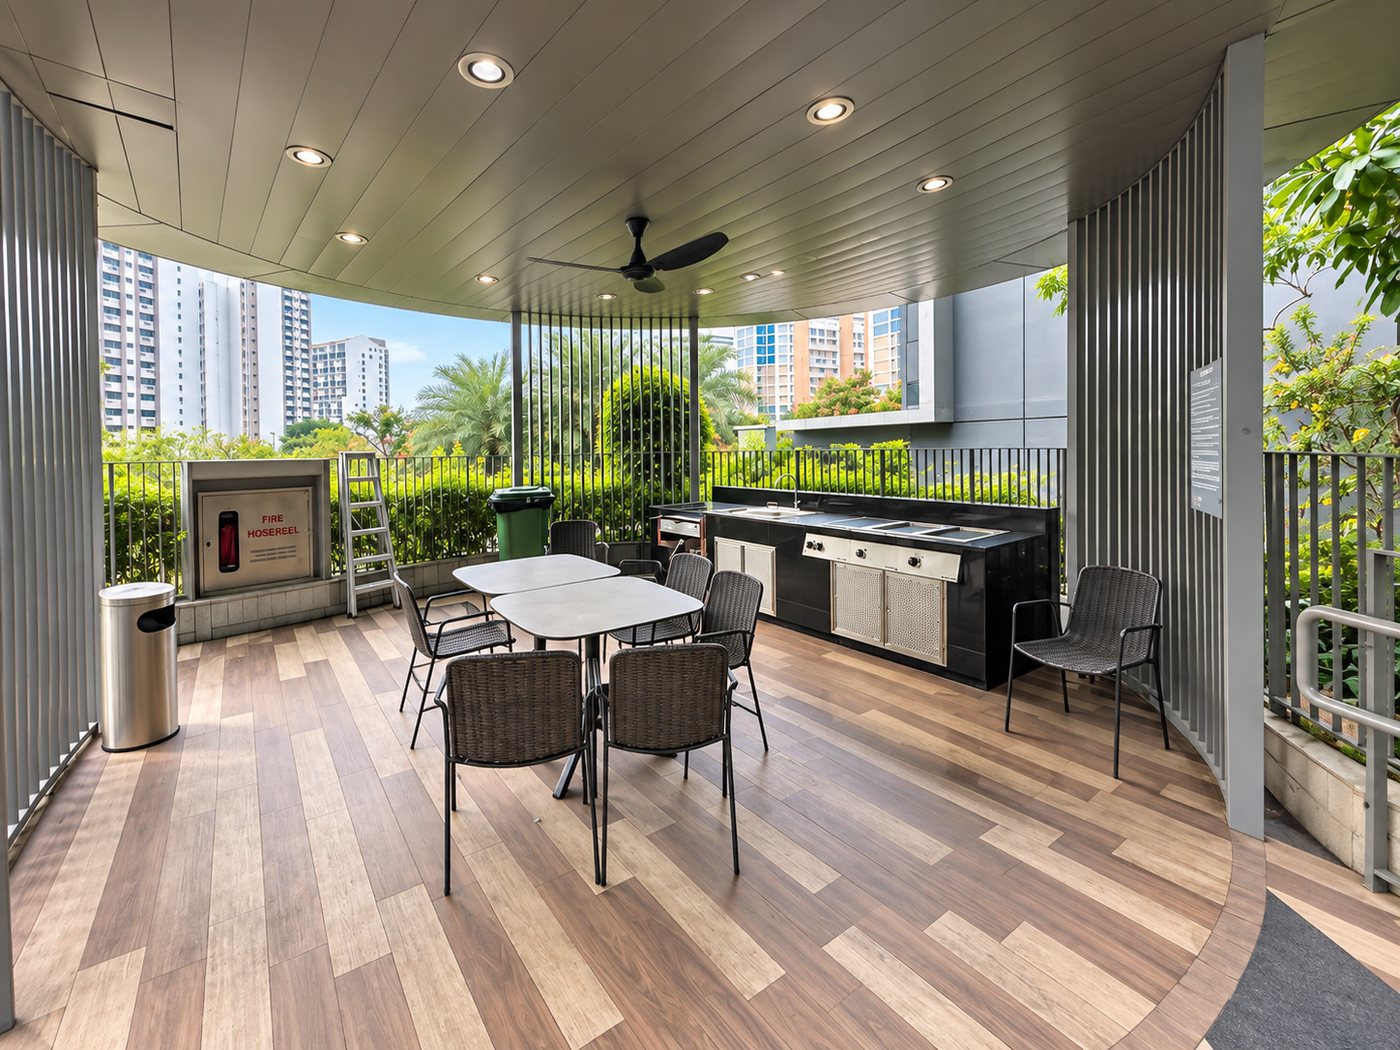
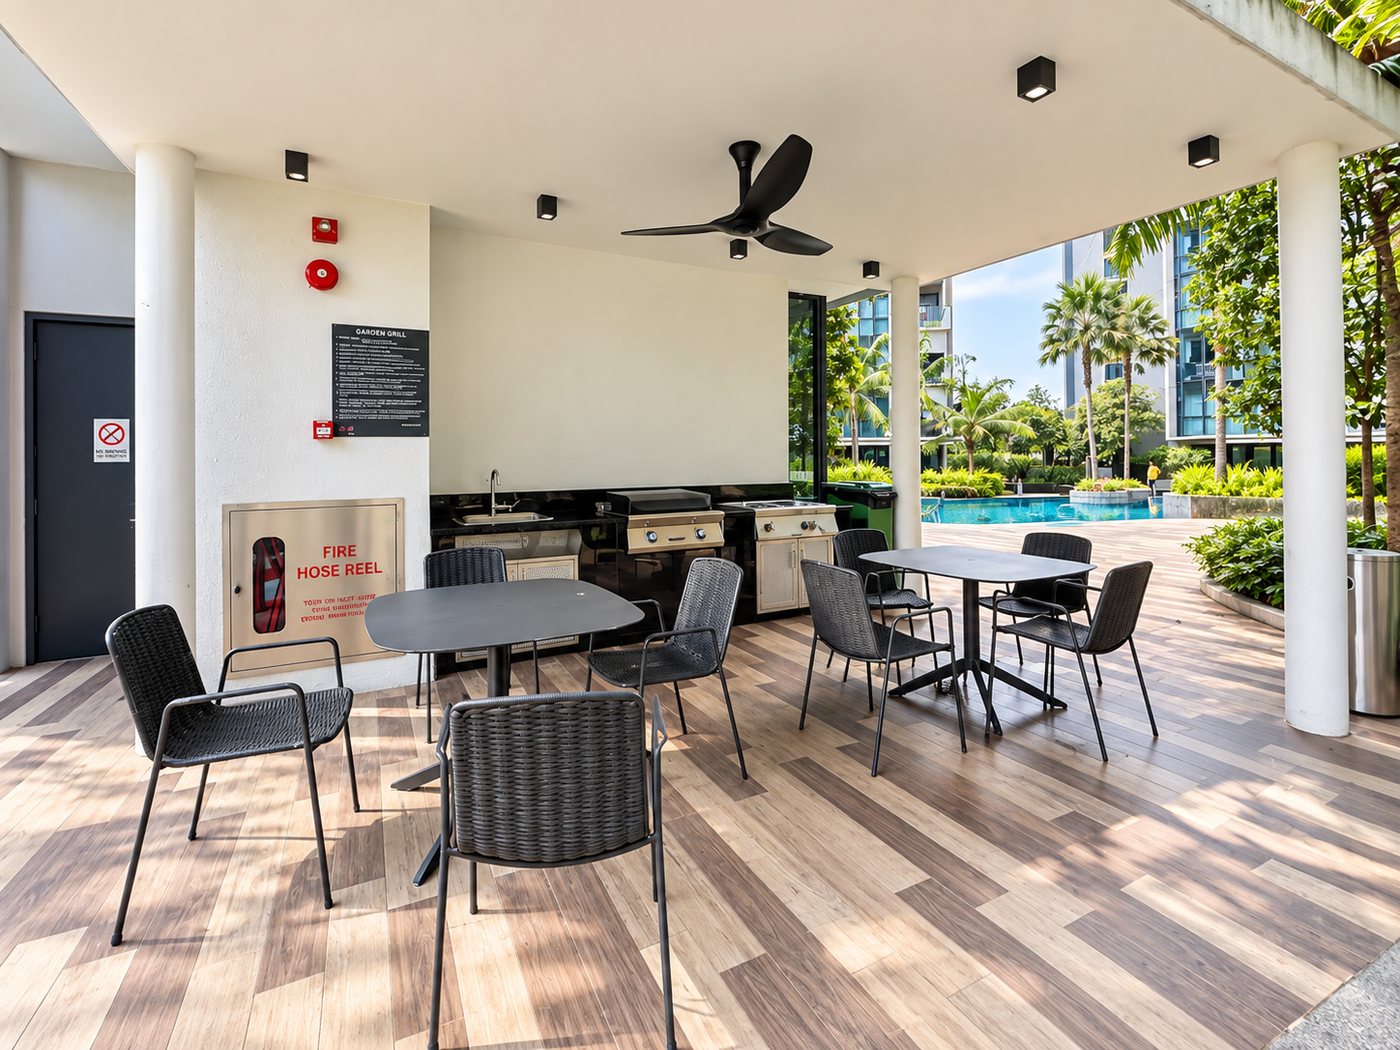
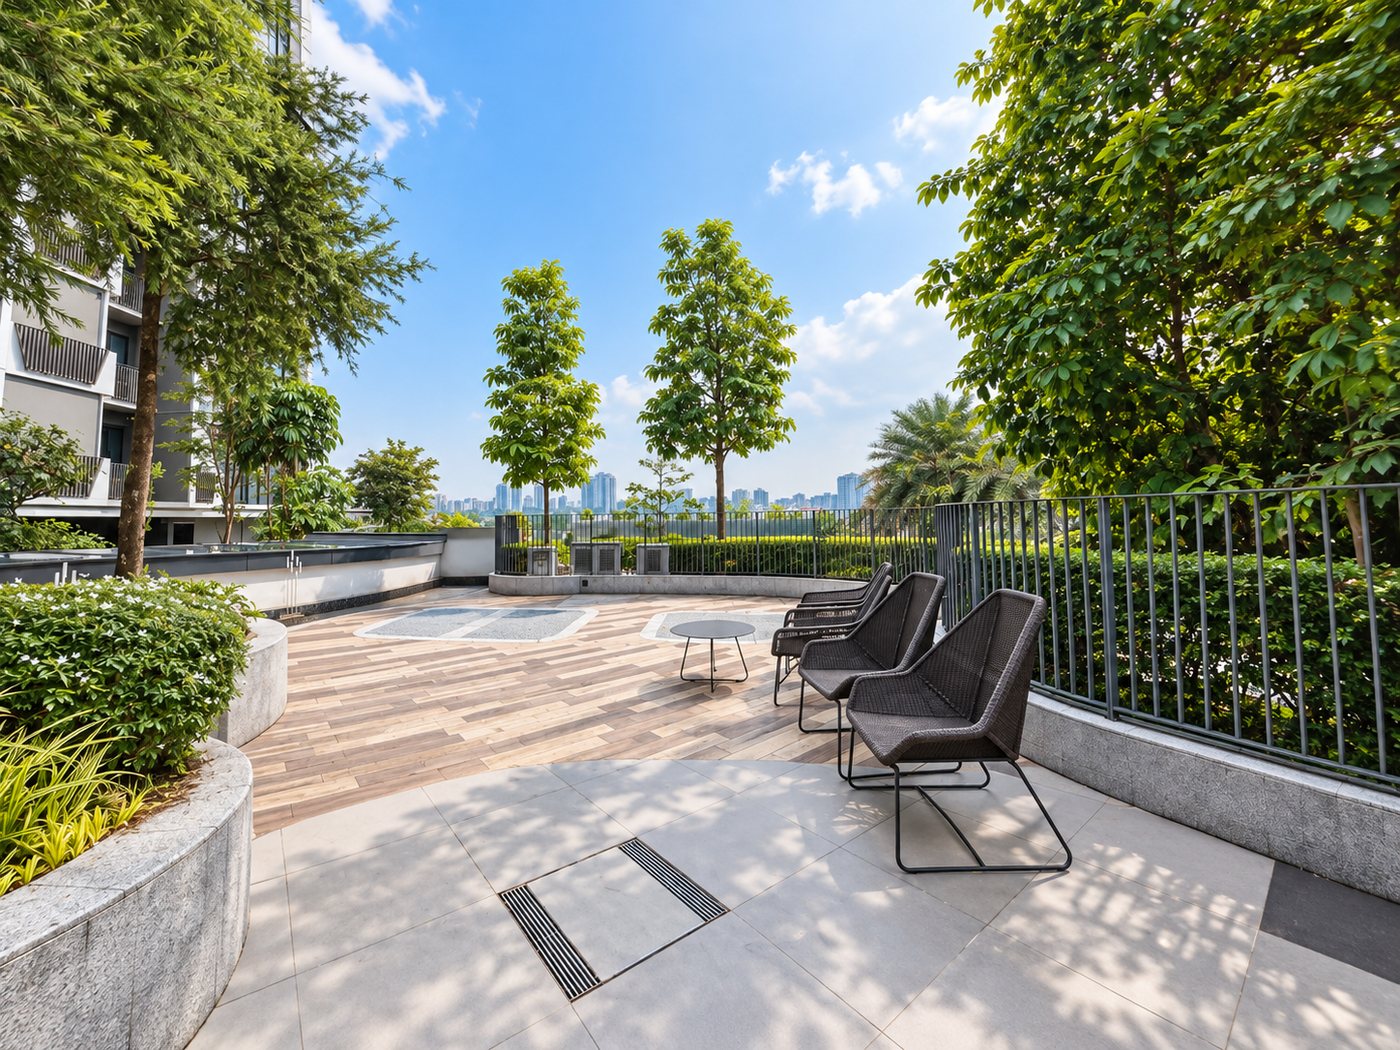
TOP was 2021, so these are not show-flat renders and not a twenty-year-old resale either. Full-height mirrored cabinetry, frameless shower screen, and the original fittings still in service.
One-bedders here run 452 sq ft. Three separate reviewers mention the rooms being compact, which is worth knowing before a viewing rather than discovering at one.
Every photograph here is the actual unit and the actual facilities, shot on site on 24 September 2026. Nothing is staged, rendered or borrowed from the developer. The rooms are empty because the unit is empty.
09 · Schools and practicalities
Zhonghua Primary. 540m
Rosyth School. 790m
Full-sized tennis court · pet-friendly community · rooftop terrace · smart-home system · QR guest registration · visitor parking at B2
Who put this together
If you are looking at The Garden Residences, or weighing it against somewhere else, I will walk you through all of it on your actual numbers, including the option of staying where you are. Come together if you can. It is usually a decision for both of you.